Published: November 18, 2026
Last Updated: November 18, 2026
Quick Answer: What Is a Key Facts Statement?
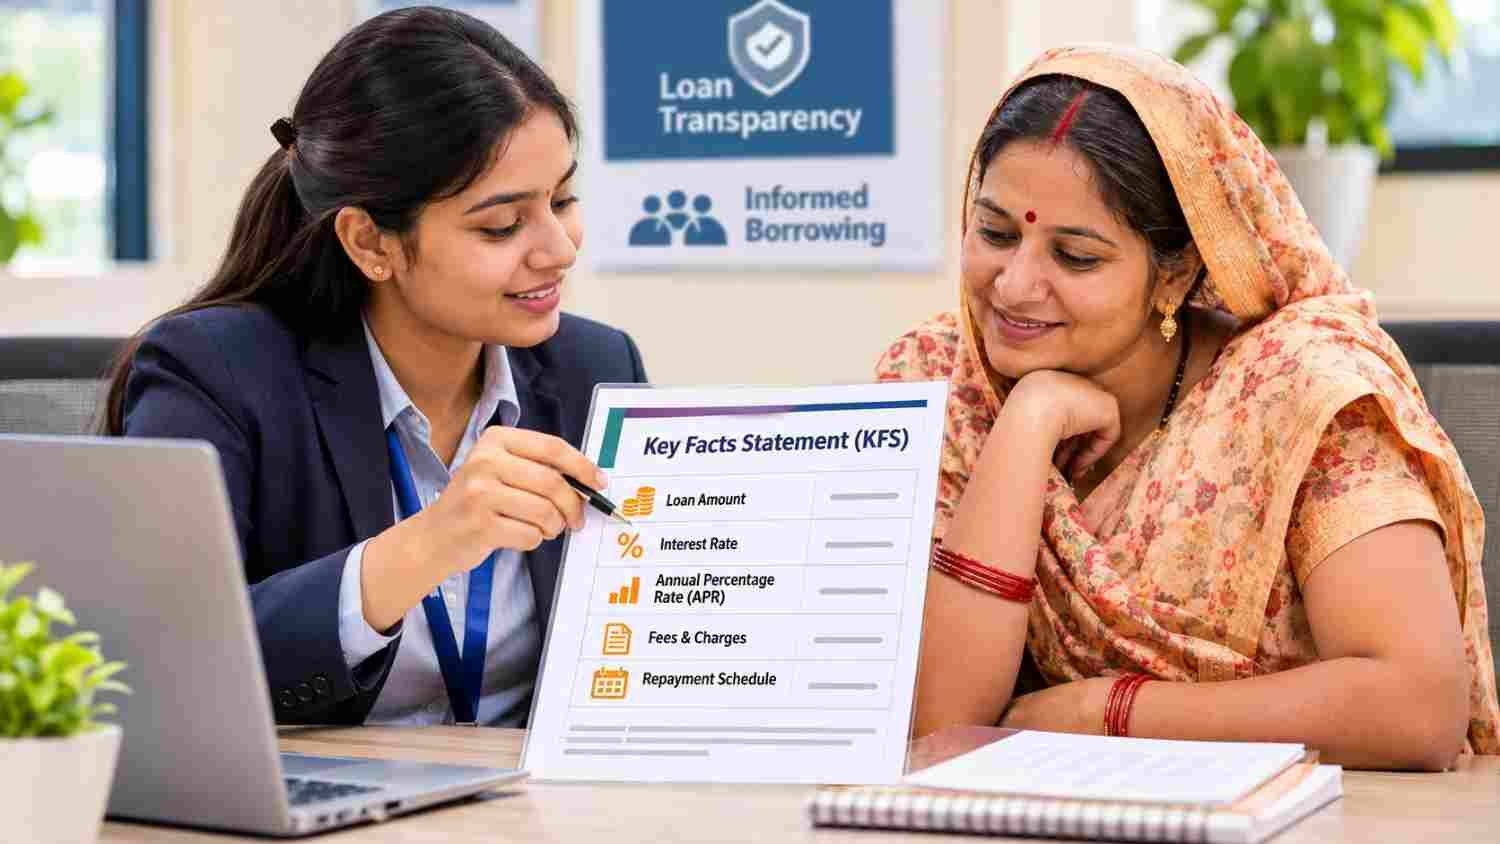
A Key Facts Statement (KFS) is a standardised document that summarises important loan information in simple language. It helps borrowers understand the interest rate, Annual Percentage Rate (APR), applicable fees, instalment amounts, repayment schedule, and other important charges before accepting a loan. Under applicable RBI directions, regulated lenders must provide and explain the KFS to prospective borrowers so they can make an informed borrowing decision.
Who should read this guide? This article is for first-time borrowers, microfinance customers, rural households, salaried individuals, students, and people comparing loan offers. It is particularly useful before signing a loan agreement, accepting a digital loan, checking processing fees, or comparing the total cost of borrowing. The guide explains what to look for in a KFS and which details borrowers should clarify with their lender.
When applying for a loan, many borrowers focus mainly on the amount they will receive and the instalment they must pay. However, the interest rate, additional charges, insurance costs, repayment dates, and other conditions also affect the total borrowing cost.
A Key Facts Statement makes these important details easier to review before a loan agreement is accepted. Understanding this document can help borrowers identify the actual cost of credit rather than relying only on verbal explanations or promotional loan offers.
Key Takeaways
A KFS summarises important details of a loan in a standardised format.
APR reflects the annual cost of credit, including interest and applicable charges.
The repayment schedule helps borrowers understand instalments across the loan tenure.
Applicable third-party charges should be disclosed separately and included in APR as required.
Charges not disclosed in the KFS generally cannot be levied under the applicable RBI directions without the borrower's explicit consent.
Microfinance borrowers should also understand their loan card and simplified pricing factsheet.
Always read the KFS and loan agreement before accepting a loan.
What Is a Key Facts Statement in a Loan?
A Key Facts Statement is a document that presents the key terms and financial details of a loan in a standardised format.
The Reserve Bank of India introduced harmonised KFS requirements to improve transparency and help borrowers understand loan products before entering into a contract.
For applicable regulated lending products, the document provides information about the loan amount, tenure, interest rate, fees, APR, instalment details, and repayment schedule.
The KFS is intended to make loan information easier to understand and compare. It should be written in a language the borrower understands, and the lender must explain its contents and obtain acknowledgement that the borrower has understood them.
Why Is a KFS Important for Borrowers?
A loan may appear affordable when the borrower looks only at its advertised interest rate or monthly instalment. However, other charges can affect the amount received and the total repayment.
A KFS helps borrowers examine:
How much has been sanctioned.
What interest rate applies.
What additional fees and charges are payable.
How much money will actually be disbursed.
What APR applies to the loan.
How much the borrower will repay over the loan tenure.
When instalments are due.
This information supports a more informed decision before the borrower signs the agreement.
Which Loans Require a Key Facts Statement Under RBI Rules?
RBI's April 15, 2024 circular harmonised KFS instructions for retail and Micro, Small and Medium Enterprise (MSME) term loans provided by regulated entities.
The requirements apply to new retail and MSME term loans sanctioned on or after October 1, 2024, including fresh loans to existing customers. Credit card receivables are excluded from the provisions of that circular.
The RBI's directions also contain specific KFS provisions for applicable microfinance lending.
Borrowers should remember that the exact requirements depend on the type of loan, the regulated lender, and the applicable RBI directions. Not every financial product follows identical disclosure rules.
For details, refer to the RBI's official KFS circular dated April 15, 2024.
What Details Should You Check in a Key Facts Statement?
Do not look only at the interest rate. Review the complete document before accepting the offer.
If any detail is unclear, ask the lender to explain it before signing.
What Is APR and How Is It Different From the Interest Rate?
Annual Percentage Rate (APR) represents the annual cost of credit to the borrower, including the interest rate and other applicable charges associated with the credit facility.
The interest rate alone does not necessarily show the complete cost of borrowing.
For example, two loan offers may have similar stated interest rates but different processing fees or other charges. Their APRs may therefore differ.
Illustrative Example: Interest Rate vs APR
Consider a hypothetical loan:
These amounts are illustrative, not an actual loan quotation. The APR must be calculated using the applicable cash flows, repayment dates, and regulatory methodology. It should not be estimated simply by adding the fee percentage to the stated interest rate.
When comparing offers, review the APR computation sheet and complete repayment schedule rather than relying on the interest rate alone.
Which Fees and Charges Should You Check Before Signing?
Loan charges can affect how much money you receive and how much you eventually repay.
Depending on the product and applicable rules, a KFS may disclose:
Processing Fees
A lender may charge a processing fee for evaluating and processing a loan application. Check the amount and whether it is deducted before disbursement or collected separately.
Insurance Charges
Some loan products may involve insurance-related charges. Verify whether insurance is compulsory or optional under the relevant product conditions, what it covers, and who receives the premium.
Legal or Third-Party Charges
Where a regulated lender recovers third-party charges, such as applicable insurance or legal expenses, the charges must be disclosed separately and included in APR as required by RBI directions. Receipts and related documents should also be provided where applicable.
Late Payment and Penal Charges
Review the consequences of missing a payment. Check how delayed-payment charges are calculated and when they apply.
For applicable NBFC loans, RBI directions require penal charges to be disclosed clearly under the relevant rules. In microfinance loans, delayed-payment charges, if any, must be applied to the overdue amount rather than the entire loan amount.
Prepayment Charges
Check whether paying the loan early or closing it before the scheduled date involves any charge. Applicable rules vary by loan category and lender. RBI directions prohibit prepayment charges on microfinance loans, while other loan products follow their applicable rules.
How to Read a Loan Repayment Schedule
A repayment schedule shows how the borrower is expected to repay the loan throughout its tenure.
It helps answer practical questions, such as:
How many instalments must be paid?
What is the amount of each instalment?
When does repayment begin?
What are the payment due dates?
How much principal and interest are included in each instalment?
What is the outstanding balance after each repayment?
For example, someone receiving a loan with monthly instalments should check the first payment date, the number of instalments, and the amount due each month.
If the KFS contains an amortisation schedule, compare it with the repayment terms in the loan agreement. Report any difference to the lender before accepting the offer.
How Long Is a Key Facts Statement Valid?
Under the RBI's harmonised KFS directions, the statement must have a minimum validity period depending on the loan tenure:
The validity period is the time available to the borrower to accept the loan terms after receiving the KFS.
The KFS must also have a unique proposal number. When a borrower agrees to the terms during the validity period, the regulated entity is bound by the terms mentioned in that statement, subject to the applicable directions.
This allows borrowers to review the details instead of feeling pressured to sign immediately.
What Happens If a Lender Mentions Charges Missing From the KFS?
Under the applicable RBI KFS directions, fees and charges not mentioned in the KFS generally cannot be charged during the loan tenure without the borrower's explicit consent.
If someone informs you about an additional payment, ask for:
The reason for the charge.
The amount payable.
The written contractual basis.
Whether the charge is covered by the KFS or a separately agreed term.
An official receipt for the payment, where applicable.
Do not pay an unexplained amount simply because someone claims it is mandatory. Contact the regulated lender through its official complaint or customer-support channel if the explanation is unclear.
Is a Microfinance Loan Card the Same as a KFS?
No. They are related disclosure documents, but borrowers should not assume they are interchangeable.
RBI's microfinance directions require regulated entities to provide borrowers with a loan card containing important information, including:
Information identifying the borrower.
A simplified factsheet on loan pricing.
Other terms and conditions attached to the loan.
Acknowledgements of repayments, including instalments received and final discharge.
Grievance-redressal details, including the name and contact number of the nodal officer.
The loan card entries should be in a language understood by the borrower.
The KFS, on the other hand, sets out the key financial terms of an applicable loan in a standardised format. It includes APR and the repayment schedule under the relevant directions.
Microfinance borrowers should review the applicable KFS, loan card, and loan agreement together, rather than assuming one document replaces the others.
For more detail, read the RBI's Regulatory Framework for Microfinance Loans.
What Should You Do Before Accepting a Loan?
Use this checklist before signing a loan agreement:
Confirm that the loan amount matches the amount discussed.
Check the interest rate and APR separately.
Review all disclosed processing and third-party charges.
Confirm the net amount expected to be disbursed.
Understand the instalment amount and repayment dates.
Check the total repayment over the full loan tenure.
Review late-payment and prepayment conditions.
Ask the lender to explain anything you do not understand.
Check that the document is in a language you can understand.
Keep copies of the KFS, loan agreement, and repayment schedule.
Taking these steps can help prevent misunderstandings and make it easier to compare available loan offers.
How Sukham Microfinance Can Help You Understand Loan Information
Understanding loan disclosures is an important part of responsible borrowing. Customers should know the amount they are receiving, the total cost of credit, the repayment schedule, and the conditions attached to the product.
You can review Sukham Microfinance's loan products to understand the listed financial solutions. The product page also notes that its repayment estimator displays principal-only figures and excludes interest and fees. Therefore, borrowers should request and review the complete repayment schedule before accepting an offer.
Learn more about Sukham Microfinance and its approach to financial inclusion before exploring its available financial solutions.
For questions about a specific product, eligibility, charges, or repayment conditions, contact the team through the official Sukham Microfinance Contact Us page.
Always confirm which regulated lender is providing the loan and which entity is responsible for issuing the applicable KFS and loan agreement.
Conclusion
A Key Facts Statement helps borrowers understand important loan details before accepting a financial commitment. It brings together information about APR, interest, applicable charges, instalments, and repayment schedules so that borrowers can make informed decisions.
Before signing a loan agreement, compare the APR, check all fees, understand the repayment conditions, and ask questions about anything unclear. Microfinance borrowers should also review their loan card and pricing factsheet.
Responsible borrowing begins with understanding the complete cost of a loan, not just the amount offered or the advertised interest rate.
Latest Blogs
You may also find these articles helpful:
UPI Safety Tips for First-Time Users in India: How to Avoid Payment Scams
Joint Liability Group Loan in India: Meaning, Process and Member Responsibilities
Managing Seasonal Business Cycles: How a Business Loan Can Help Your Growth Strategy
How to Check Your CIBIL Score and Correct Errors in Your Credit Report
How to Identify Fake Loan Apps and Digital Lending Scams in India